

Raising money for an InsurTech startup comes with a few considerations that founders in other sectors never have to think about. Insurance is a specialized industry where distribution, regulation, and partnerships all take time, and depending on what you are building you may also need carrier relationships, reinsurance, capacity, licenses, actuarial expertise, or a way in to brokers. That makes your choice of investor more consequential than it would be for most companies.
A high valuation or a large check is attractive. What the investor does after the round closes is usually worth more. An investor with insurance expertise, relevant relationships, and experience of the industry’s particular problems can be far more useful than a generalist offering capital alone, and no single investor provides everything a startup needs. This is sometimes called smart capital: money combined with knowledge, industry access, and practical support.
Sokhiba Mukhitdinova, Investment Principal at InsurTech Fund, encourages founders to think about the investor group as a whole: build a complementary set of investors, and be clear about what a new one adds that is currently missing. Her colleague Vanessa Fajardo, Investment Analyst, adds the test for any individual investor: what can they bring beyond money, and the real answer tends to show up during the tougher periods rather than the good ones.
If you’re evaluating an InsurTech venture fund for your next round, here are seven things worth understanding.
What is an InsurTech venture fund?
An InsurTech venture fund is a venture capital fund that invests specifically in startups building technology, products, infrastructure, or new business models for the insurance industry. Specialist funds typically combine capital with insurance expertise, industry relationships, and strategic support.
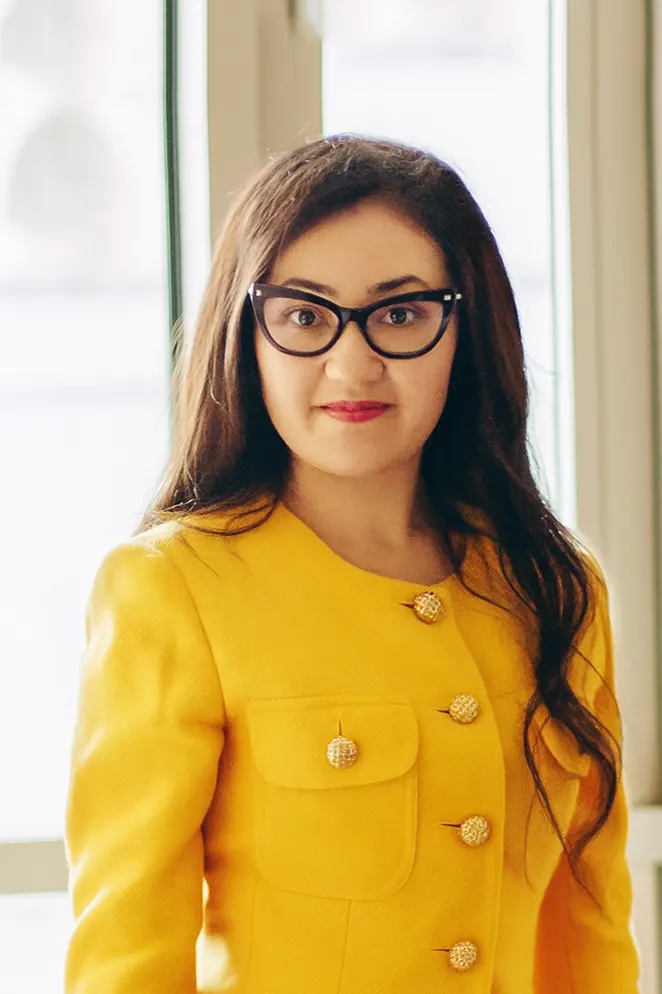
Sokhiba Mukhitdinova
Sokhiba works with early-stage insurance and InsurTech companies across investment sourcing, evaluation, and portfolio development.
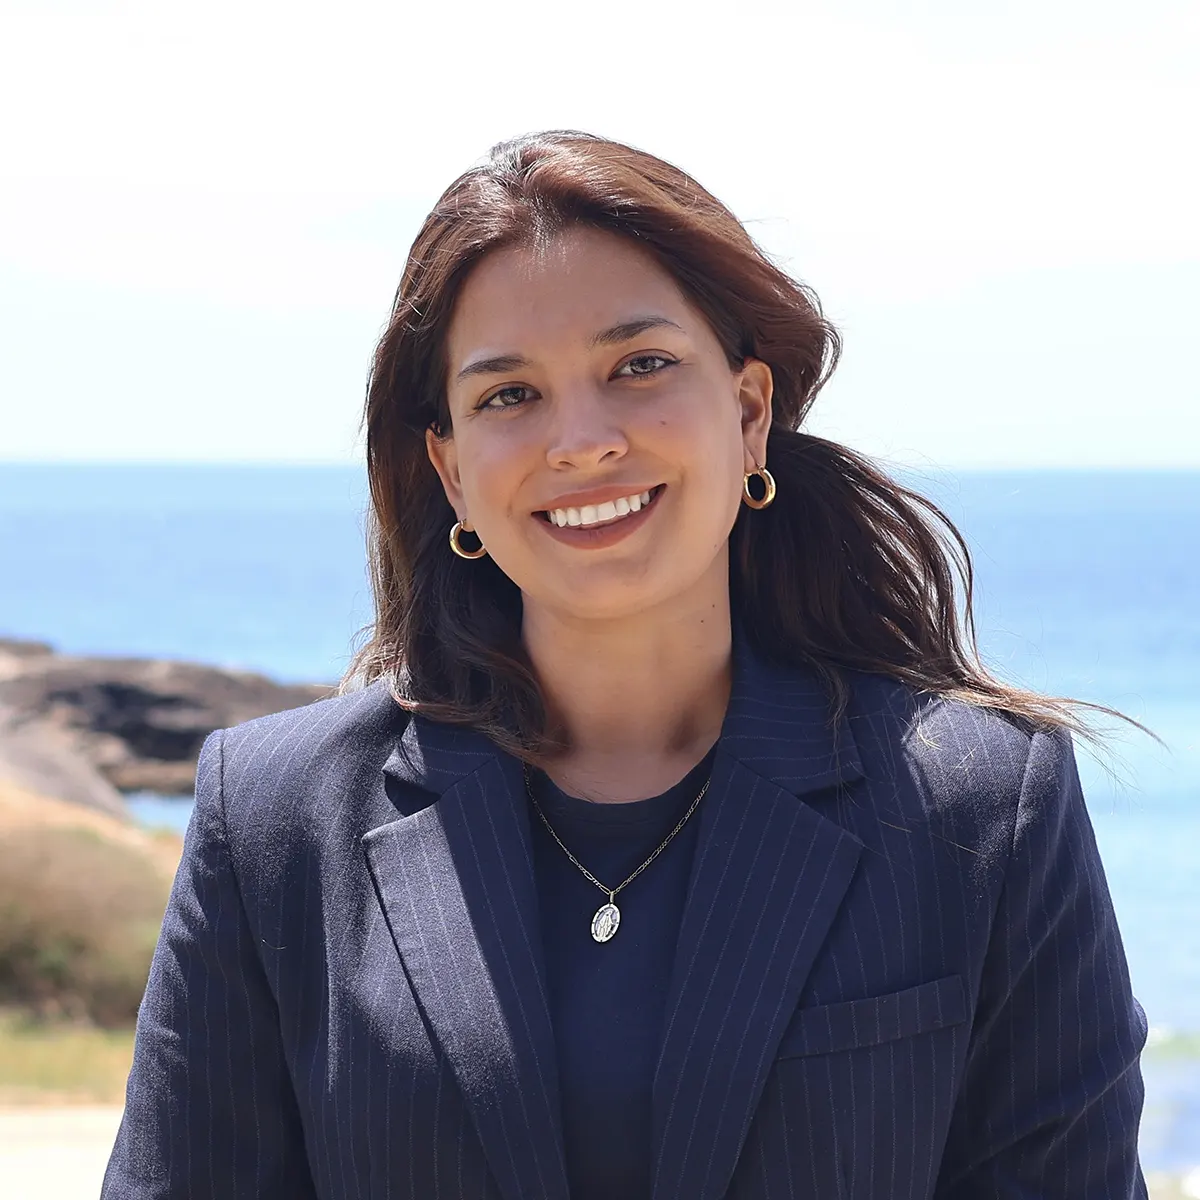
Vanessa Fajardo
Vanessa is part of the InsurTech Fund investment team, working with early-stage insurance and InsurTech founders. Connect on LinkedIn · Meet the team
“InsurTech” is a much broader category than it sounds
Two companies can both call themselves InsurTech startups and have almost nothing in common. One builds software for commercial carriers. Another is launching an MGA. Others are building AI for claims, employee benefits technology, embedded insurance infrastructure, underwriting tools, new distribution models, or catastrophe risk products. An investor who understands one of those businesses won’t necessarily understand the others.
So look past whether a fund says it invests in “insurance technology” and read its portfolio and the backgrounds of the people making the decisions. Check whether they have backed a company with your business model, whether they understand your customer, and whether they have worked in the part of the value chain you are trying to change. Sector fit is far more specific than the label on a website.
Stage fit matters just as much as sector fit
An investor can know insurance exceptionally well and still be the wrong investor for your round. Early-stage InsurTech investors concentrate on pre-seed and seed. Growth investors back companies that already have meaningful revenue and are raising Series A or later. Some funds span several stages but write very different checks depending on the opportunity. Before you spend weeks pursuing a fund, find out its:
- Typical first check size
- Preferred investment stage
- Revenue or traction expectations
- Ownership targets
- Whether it typically leads rounds
- Whether it reserves capital for follow-on investments
Then ask the longer-term question:
Insurance expertise can shorten the learning curve
Insurance has more nuance than most industries. A generalist investor may understand SaaS economics, marketplaces, or enterprise software extremely well; what a dedicated insurance investor adds is familiarity with the environment that software has to operate in. They already know why carrier procurement takes so long, how brokers evaluate new products, why capacity becomes a bottleneck for an MGA, and why an integration that looks simple on paper gets complicated inside a large carrier.
That saves founders months of explaining the basics, so conversations move faster to what makes the company different. Specialist investors can also contribute to the product itself. Their relationships with carriers, brokers, underwriters, and actuaries give founders a way to test assumptions, understand customer requirements, and spot the features or product structures that become an advantage. This matters most for founders building insurance businesses rather than selling technology into insurance. Programs such as the InsurTech NY MGA Lab exist for the same reason: building an MGA requires expertise across underwriting, capacity, distribution, regulation, and product, not just startup execution.
The investor’s network can matter almost as much as the check
For an early-stage company the right introduction can be worth more than the money, and this is where a specialist InsurTech investor has the clearest edge. Depending on the business, that might mean access to:
- Carriers and reinsurers
- Brokers and agencies
- Capacity providers
- Potential customers and distribution partners
- Insurance executives and subject-matter experts
- Other founders who have solved similar problems
- Future investors
“We have a strong network” is easy to put in a pitch deck, so ask what it looks like in practice: who the fund works with regularly, how portfolio companies actually get in front of those people, and whether the investor can point to partnerships, customers, or hires that came through it. Those answers tell you more than anyone’s LinkedIn connection count.
“Strategic support” should mean something specific
Almost every venture fund promises to help its founders. Vanessa’s test is what that help looks like when the plan slips:
Investors work very differently after the round closes. One is heavily involved in strategy and fundraising; another concentrates on industry introductions; others provide recruiting help, product expertise, regulatory knowledge, or board-level guidance. None of those models is wrong, but you should know which one you’re getting. Ask how often they work with portfolio founders, where they think they are most useful, and what they have actually done for companies at your stage. Support an investor can’t describe with examples probably isn’t there.
Look at the portfolio, not just the pitch
The quickest way to understand a fund is to look at what it has already invested in. Note the stage those companies were at when the fund came in, the insurance markets they serve, their business models, and where they operate. Then the practical questions: does the fund already hold a stake in a potential competitor? Has it made follow-on investments? Does it stay involved after the round? Are portfolio companies visibly connected to the fund’s wider network?
If you can, talk to a few portfolio founders and ask what the investor was like during fundraising and, more importantly, afterward. A portfolio shows you what a fund likes to back and how it behaves once it has.
Founder fit still matters
A dedicated InsurTech fund isn’t automatically the right investor because you’re building an InsurTech company. An investment is a relationship that lasts for years, so you need to understand how the investor thinks about growth, governance, future fundraising, and exits, and how they behave when things don’t go to plan. References work both ways in venture capital, and other founders can answer the questions a fund’s website won’t:
- Does the investor respond when something goes wrong?
- Are they useful between rounds?
- Do they make the introductions they promise?
- How do they handle disagreement?
- Do they know when a company needs patience rather than pressure?
Insurance expertise and industry connections are valuable. You still need to want that investor around the table.
Questions to ask an InsurTech investor
If you’re evaluating investors for a pre-seed or seed round, a few direct questions reveal a lot.
Finding the right InsurTech venture capital partner
Dedicated InsurTech funds aren’t the only source of capital for insurance technology startups. Generalist venture funds, corporate venture arms, strategic investors, angels, and insurance executives all have a place on a cap table. What a specialist investor offers is capital combined with people who already understand the industry you’re entering, and that is worth most at the earliest stages.
The strongest investor group is usually a mix: one investor with insurance relationships, another with technology experience, another with later-stage fundraising expertise, and perhaps a strategic who knows one corner of the market well. The goal isn’t an investor who understands InsurTech. It’s investors who understand your part of it and, together, provide what your company needs next.
Early-stage capital built around the insurance ecosystem
The InsurTech Fund invests in early-stage companies building across insurance and risk, from pre-seed through Series A, with seed as its primary focus.
Connected to the broader InsurTech NY ecosystem, the Fund operates within a community of insurance carriers, brokers, founders, investors, and industry leaders, which gives portfolio companies relationships across the insurance market alongside the capital.
The investment team combines backgrounds across venture capital, insurance, technology, and industry innovation. You can meet the InsurTech NY and InsurTech Fund team, including Investment Principal Sokhiba Mukhitdinova and Investment Analyst Vanessa Fajardo.
If you are building an InsurTech startup in the United States, United Kingdom, or Canada, we would be happy to hear from you.